

OneMain Financial
by OneMain Financial
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
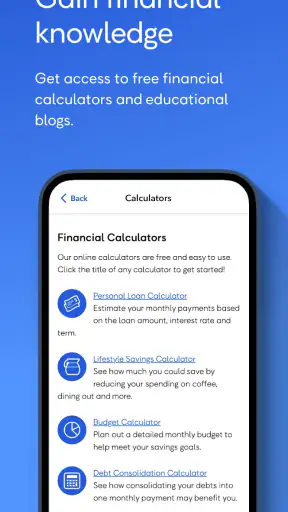
 Analysis by Getfullapps
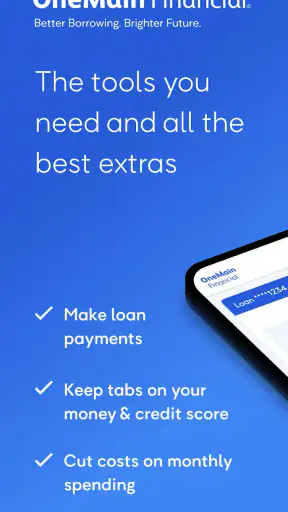
Managing a personal loan from a phone sounds simple, but the real test is what happens when a payment screen does not behave as expected, a balance looks unfamiliar, or credit information takes time to update. I spent time looking at OneMain Financial as a practical finance app rather than treating it as just another account shortcut. Its purpose is focused: it brings loan management, payments, and credit tracking into one mobile place for customers of OneMain Financial.
That focus is both its strongest quality and its clearest boundary. If you already have a OneMain loan, the app can reduce the need to search through emails, call support for routine details, or use a desktop browser for every small task. If you are looking for a general budgeting tool, a bank replacement, or a marketplace for comparing loans, this is not the right kind of product. It is a companion for an existing relationship with the developer, not a universal financial dashboard.
What using OneMain Financial feels like in everyday situations
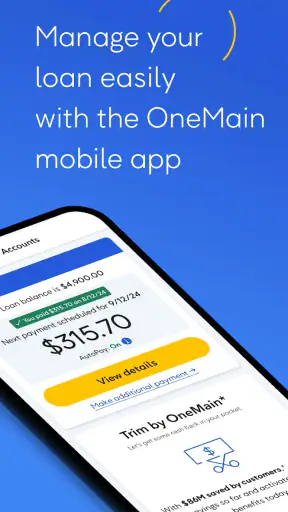
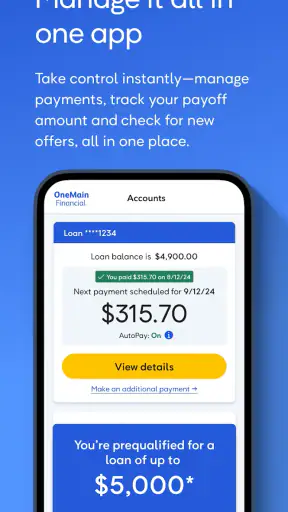
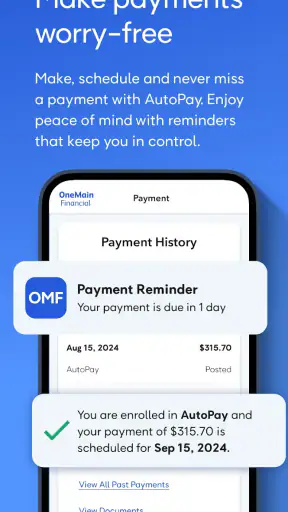
The most useful scenario is an ordinary payment day. Imagine checking your finances during a lunch break and wanting to confirm the amount due, review the loan status, or make a payment without opening a laptop. A dedicated loan app is valuable here because it keeps the task narrow. I do not have to sort through unrelated spending categories or investment screens before reaching the information that matters.
That same narrow design can help someone who prefers a clear routine. I would use it to check the account before moving money, complete the payment, and then return later to confirm that the activity is reflected. The important habit is not simply tapping “pay”; it is keeping a personal record of when the payment was initiated and checking the account afterward. A mobile screen makes the first part convenient, but it should not replace careful review of bank activity.
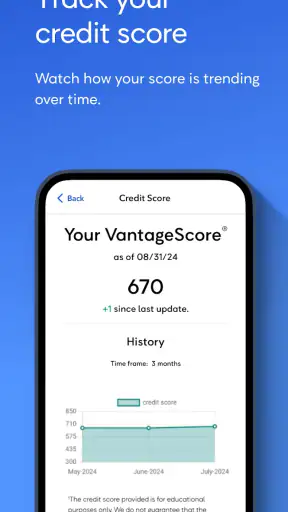
The app also makes sense for borrowers who want to keep an eye on credit-related information alongside their loan. That can be useful when preparing for a future application or trying to understand whether regular financial habits are moving in the right direction. I would treat the credit view as a monitoring aid, not as the only source for an important lending decision. Credit information can change at different times across services, so a phone display should be read as part of a wider picture.
One practical strength is that the app’s purpose is easy to understand. OneMain Financial developed it for people who need access to their loan relationship, and its store presence reflects that established role: it has more than a million installs and an average rating of 4.7 from roughly 28 thousand ratings. Those figures suggest that many customers find the basic experience useful, although a high rating does not guarantee that every payment or sign-in issue will be smooth on every phone.
Where people are most likely to get stuck
In my view, the first source of friction is account access rather than the loan tools themselves. Finance apps must connect the right person to the right account, so a small mismatch in sign-in details can stop the process before any payment option appears. I would begin by checking that I am using the same account information associated with my OneMain relationship, rather than repeatedly trying variations of an email address or password.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A second sticking point is expecting a completed action to appear instantly everywhere. A payment may be submitted in the app while the bank account, loan balance, or credit view takes longer to reflect the change. That delay can tempt people to submit the same payment again. I consider that one of the riskiest habits in any financial app: if the first attempt appears to have gone through, I would save the confirmation details and wait for the account activity to settle before trying again.
There is also a difference between seeing a loan detail and changing the underlying financial arrangement. A mobile interface can make account information accessible, but it does not turn every request into an instant self-service action. If the issue involves a disputed amount, a payment that needs correction, or a question about loan terms, the app may be the best starting point for reviewing the account, while direct assistance may still be the better route for resolution.
Setup checks that prevent avoidable trouble
Before relying on the app for a time-sensitive payment, I would install it on a phone running a supported version of the operating system. The listed minimum is Android 7.0, which covers many older devices, but compatibility is not the same as a guarantee that an aging phone will offer the best experience. I would also make sure the device has enough free space, a stable connection, and the current app version, which is 10.30.0.
Those checks sound basic, yet they matter more for a finance app than for a casual utility. If the screen freezes during a payment flow, it becomes difficult to know whether the problem is the connection, the device, or the transaction itself. I would avoid starting a payment while switching between weak Wi-Fi and mobile data, and I would not force-close the app immediately after tapping a final confirmation unless the screen is clearly unresponsive.
Another useful preparation step is organizing the information needed before signing in. I would keep the relevant account details available, use a private connection, and avoid completing financial tasks on a shared device. That is not a special feature of OneMain Financial; it is simply sensible handling for an app that displays loan and credit information. The app is rated for Everyone, but that age label describes content suitability, not a promise that every user will find the financial process effortless.
I also recommend checking the phone’s date and time settings if screens behave strangely. Incorrect device settings can interfere with session handling and make recent activity appear confusing. If an update is available, installing it before troubleshooting is sensible, but I would not uninstall the app as a first reaction when a transaction may still be processing. Preserving the current session and any visible confirmation is more useful than immediately starting over.
A safer way to recover when a workflow breaks
When a payment or account action does not finish normally, I use a simple sequence. First, I note exactly what the app displayed: an error, a loading screen, a confirmation, or no response. Second, I check whether the account activity changed. Third, I avoid repeating the action until I understand the first attempt. This approach is slower than tapping again, but it reduces the chance of creating duplicate activity.
If the app closes unexpectedly, I would reopen it once, sign in again if necessary, and look for the account history before initiating anything new. If the same screen fails repeatedly, I would switch from troubleshooting the button to checking the environment: connection quality, available storage, operating-system support, and whether the app needs updating. Repeatedly clearing and reinstalling an app can remove useful context, so I would reserve that step for situations where the account status is already clear.
For a payment that appears pending, patience is part of the workflow. I would keep the confirmation screen or reference information, record the time, and compare the result with my bank activity later. If the amount is still unclear or the account shows an unexpected status, I would contact OneMain Financial through an official support route rather than relying on an unofficial number found in a random message or forum. The app can help me inspect the account, but it cannot make an uncertain transaction safe by itself.
The same principle applies to credit tracking. If the credit view does not change immediately after a financial event, I would not assume that the app has failed or that the underlying record is wrong. Credit information can follow its own update cycle. I would use the screen for ongoing awareness and investigate a genuine discrepancy with the appropriate financial provider before making a major decision.
When the app is not the actual cause
It is easy to blame a finance app when the real issue is outside the app. A bank transfer can be delayed by the bank. A payment can be declined because of the funding account. A balance can look different because a transaction is still being processed. A credit display can lag behind other records. In each case, reinstalling OneMain Financial would not solve the underlying problem.
My first diagnostic question would be: did the app reject the action, or did the action leave the app and then fail elsewhere? That distinction changes the next step. A clear in-app error points toward checking the app, device, and account access. A completed submission followed by an unexpected bank result points toward reviewing the bank account and transaction details. Treating both situations as an app bug can lead to unnecessary duplicate attempts.
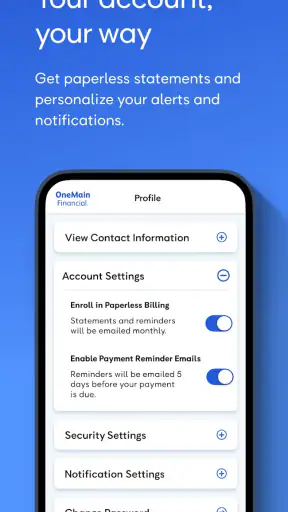
I would also be cautious about notifications. Not seeing a notification does not automatically mean that an action did not happen, just as seeing a notification does not replace checking the account. Notification delivery can depend on phone settings, connection quality, and background activity. For anything involving money, I prefer the account record and confirmation details over a banner that may disappear from the screen.
Privacy is another reason to keep expectations realistic. The app is free to download, but that does not mean it replaces the responsibilities that come with borrowing. I would still read payment information carefully, protect sign-in details, lock the phone, and avoid sharing screenshots that expose account or credit data. Convenience should shorten the process, not encourage careless handling of sensitive information.
Who will benefit most from it
I think the app is best for existing OneMain borrowers who want a direct way to manage routine loan tasks from a phone. It suits someone who checks balances frequently, prefers mobile payments, or wants a single place to review loan and credit-related information. It can also help users who dislike navigating a full financial website for a narrow job.
It is less suitable for someone comparing several lenders, building a detailed household budget, tracking accounts from multiple banks, or looking for investment management. A general personal-finance app may be better for a complete view of spending and savings. A bank’s own app may be the more natural place to monitor the funding account. A credit-focused service may offer a broader monitoring experience. OneMain Financial is strongest when the central question is, “What is happening with my OneMain loan?”
I would also hesitate to recommend relying on it as the only channel for urgent or complicated account problems. A mobile interface is excellent for routine access, but questions about disputed payments, unusual balances, or changes that require explanation may be handled more effectively through direct support. The app should be viewed as a convenient control panel, not as a substitute for every form of customer service.
How it compares with the usual alternatives
Compared with using a desktop browser, the app wins on immediacy. I can check the loan while away from a computer and handle a routine task in a more focused environment. The trade-off is that a phone screen gives me less room to compare details, inspect several records at once, or keep supporting documents visible. For a quick check, I prefer the app; for careful financial review, a larger screen may be more comfortable.
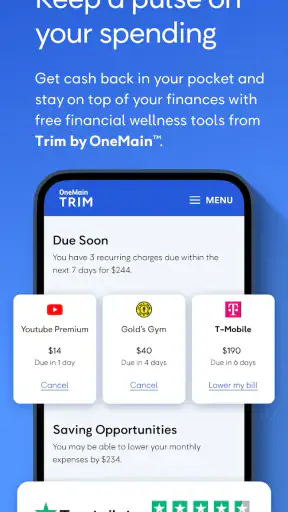
Compared with a general budgeting app, OneMain Financial offers a narrower experience. That is an advantage when I do not want unrelated accounts and spending categories competing for attention. It is a disadvantage when I need a complete picture of household cash flow. I would not choose it to replace a budget, because its value comes from staying close to the OneMain loan rather than attempting to organize every part of my financial life.
Compared with managing payments through a bank app, the OneMain option keeps the loan side closer at hand. A bank app may show the outgoing transaction clearly, but it may not provide the same loan-centered context. On the other hand, the bank app remains important for confirming whether funds actually left the account. In practice, I see these tools as complementary rather than competing: one shows the loan relationship, while the other helps verify the funding account.
Small habits that make the experience more reliable
I would use a repeatable checklist for every important payment: verify the account, review the amount, confirm the funding source, submit once, and save the confirmation. This is not glamorous advice, but it is more valuable than rushing through a polished interface. If the app shows a successful result, I would still check the account activity later instead of assuming that the process is finished everywhere.
For credit tracking, I would compare trends rather than react to one display. A single change can be difficult to interpret without context, and an update may not appear at the same time as a loan payment. I would use the app to notice questions early, then consult the relevant records before applying for credit or making a major financial choice.
Finally, I would keep the app updated and remove old screenshots or notes that contain sensitive information once they are no longer needed. The current version is 10.30.0, and staying current is a sensible way to reduce avoidable compatibility problems. I would not treat an update as a guarantee that every account issue disappears, but it is a reasonable first maintenance step when the app behaves unexpectedly.
My practical verdict
After looking at it as a real loan-management tool, I see OneMain Financial as a focused and useful app for the people it is designed to serve. It is free, comes from OneMain Financial, and has been available since April 10, 2014, giving it a long presence in the finance category. Its strongest point is not a huge collection of features; it is the convenience of bringing loan payments, account review, and credit tracking into one place.
The experience is most dependable when I use it for deliberate, routine actions and verify important results afterward. The main friction comes from account access, processing delays, device conditions, and situations that belong to a bank or support team rather than the app itself. Understanding that boundary prevents many of the mistakes people make when a financial screen does not update immediately.
I would recommend it to an existing OneMain borrower who wants simpler mobile access to a loan, but not as a replacement for a full budgeting app, bank account, or human support. If that matches your situation, the app is worth trying. Just approach payments carefully, keep confirmation details, and remember that convenience works best when paired with a quick second check.
Pros
- Loan application and account management are available through the mobile app.
- Users can view payment details, balances, and upcoming due dates in one place.
- Electronic document access can reduce paperwork and simplify record keeping.
- Autopay options may help borrowers avoid missed payment deadlines.
- Customer support and account assistance are accessible from the app.
Cons
- Loan availability, rates, and terms depend heavily on individual credit profiles.
- Late or missed payments may lead to fees and negatively affect your credit history.
- The app is mainly useful to existing OneMain customers and loan applicants.
- Some account changes may still require contacting customer service directly.
- Borrowing costs can be high compared with alternatives for well-qualified applicants.
FAQs for OneMain Financial
What is OneMain Financial, and what services does it offer?
OneMain Financial is a lending and financial services company that primarily offers personal loans. Depending on eligibility and location, users may apply for loans for purposes such as debt consolidation, home improvements, major purchases, or unexpected expenses. The app and website can also help customers review account details, check payment information, manage scheduled payments, and monitor their loan status after approval.
Can I apply for a OneMain Financial loan through the mobile app?
The OneMain Financial mobile experience may allow eligible customers to begin or manage parts of the loan process, although availability can vary by state, account type, and current app features. Applicants generally provide personal, employment, income, and banking information for identity and eligibility checks. Approval is not guaranteed, and you should carefully review the proposed amount, interest rate, fees, repayment term, and total cost before accepting an offer.
What credit score is required to qualify for OneMain Financial?
OneMain Financial does not rely on a single publicly guaranteed minimum credit score for every applicant. Approval decisions may consider your credit history, income, existing debts, employment, requested amount, and other information. Some applicants with less-than-perfect credit may be considered, but a lower credit profile can result in a higher interest rate or less favorable terms. Prequalification, when available, may help you review potential offers without immediately committing.
Does checking my options with OneMain Financial affect my credit score?
The effect depends on the specific stage of the application. OneMain Financial may offer a preliminary inquiry or prequalification process that uses a soft credit check, which typically does not affect your credit score. If you proceed with a formal application or accept a loan, a hard credit inquiry may be required and could temporarily influence your score. Always read the disclosure shown during the application before submitting your information.
Are OneMain Financial personal loans safe, and what should I check before downloading the app?
The official OneMain Financial app can provide a convenient way to access loan information, but users should download it only from the legitimate Google Play Store or Apple App Store listing and verify the publisher name. Before borrowing, compare the annual percentage rate, origination or other fees, monthly payment, late-payment consequences, and total repayment amount. Never share passwords or verification codes with anyone contacting you outside official support channels.

OneMain Financial
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via appfeedback@onemainfinancial.com, visit https://www.onemainfinancial.com, or review their https://www.onemainfinancial.com/legal/privacy-policy.










